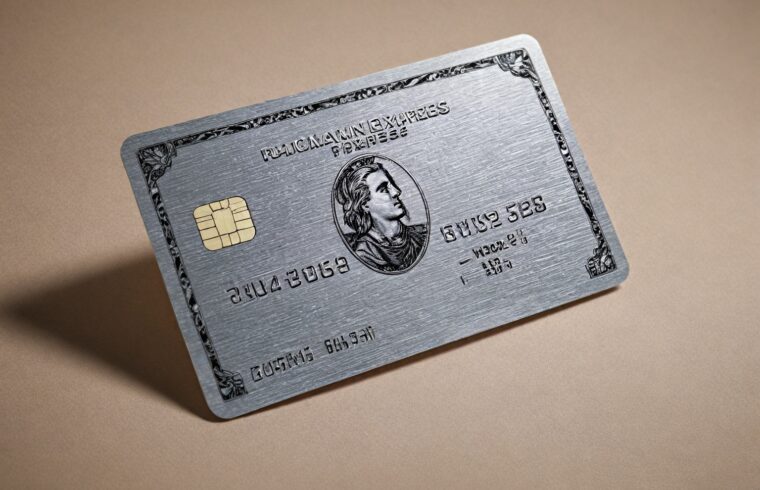
American Express Platinum Business Card.
Courtesy: American Express
American Express has recently unveiled significant updates to its flagship Platinum card, designed to cater to the affluent segment of the market. This move comes amidst growing competition among credit card issuers targeting high spenders in the United States. The updated consumer and business versions of the card will now feature an annual fee of $895, reflecting an increase of 29% from the previous fee of $695. While the hike in fees may raise eyebrows, American Express promises a remarkable $3,500 in annual benefits that consumers can utilize through various credits connected to their card purchases.
The revised benefits landscape includes perks linked to popular brands and services such as Uber, Lululemon, Oura, and the restaurant reservation platform Resy. In addition, enhanced hotel rewards and streaming credits have also been introduced. According to Howard Grosfield, president for U.S. consumer services at American Express, none of the prior benefits have been rolled back, ensuring that existing cardholders will enjoy these new additions alongside previous features.
American Express’ announcement underscores an escalating battle in the premium card market as financial institutions vie for the attention of wealthy consumers. Recently, both JPMorgan Chase and Citigroup have also updated or launched new premium credit cards that are packed with appealing rewards for frequent travelers and big spenders. This intense competition reflects a shift in spending dynamics, with affluent consumers now accounting for a growing portion of the nation’s overall spending—reportedly covering 50% of such expenditures recently, a figure not seen in over thirty years.
Unlocking Perks
Despite the increased membership cost, there is concern that some users may downgrade to lower-tier cards or explore more budget-friendly options offered by companies like Capital One or Citigroup. This sentiment has been echoed by analysts who note the potential backlash against the “coupon book” approach, which demands an active effort from cardholders to maximize rewards. Indeed, discussions in various online forums have highlighted frustrations regarding the complexity of fully utilizing the offered benefits.
Addressing these concerns, American Express has introduced a new app feature aimed at helping Platinum cardholders easily access and set up their benefits. Grosfield reassures customers that tremendous effort has been invested in simplifying the user experience to unlock rewards and enhance card member satisfaction. Notably, current Platinum cardholders will face the increased fee upon renewal starting from January 2, indicating that the updates will soon impact a larger audience.
Future Implications and Solutions
The heightened competition and premium offerings imply that credit card companies are banking on affluent Americans to drive an ever-increasing share of total consumer spending. This race to enhance card offerings may lead to a more competitive landscape that, while beneficial for consumers through improved incentives, also raises questions about sustainability. Will these increased fees deter some users, prompting long-term loyalty challenges for card issuers?
As financial institutions innovate to cater to high-net-worth individuals, exploring feedback from existing customers will be crucial in maintaining a positive relationship. Solutions may involve ongoing adjustments to benefits structures or enhanced engagement strategies to ensure that cardholders fully understand and can utilize their card’s offerings effectively. The results of this competitive renewal will likely reshape the credit card industry’s landscape and set new standards for customer expectations and service in the coming years.
In summary, American Express’s substantial revamp of its Platinum card highlights a strategic response to a shifting consumer landscape dominated by affluent spenders. As competition intensifies, questions remain about whether the rising costs and complex benefits won’t hinder customer loyalty. How will other credit card issuers respond to these premium offerings? Will consumers find value in the enhanced benefits enough to justify their expenditure? The future of credit cards and the strategies of issuers may depend on how well they adapt to these challenges.
Editorial content by Evelyn Martinez